

When Amazon talks about 'consistency,' it does not mean asking you to fill in the same string of characters in every address field in the backend; it means whether the same business entity can be reconstructed as the same company across tax records, payment institutions, identity documents, and logistics documents. The backend information is only one copy of it, and what the platform really does is cross-corroborate these copies.
The most common order of exposure looks like this: the address entered in DAC7 address verification or address validation differs from the registered address on the business license, and 'information pending verification' appears first; after you submit additional documents, you are told that the supporting documents cannot be matched, and then payments are suspended or funds are placed on reserve; further down the line, the account enters review; if other accounts are also logged in within the same browser environment, they may also be asked to provide additional verification.
Every link in this chain points to the same thing: the information does not match, so the platform suspects the payment flow first, and then suspects the account itself.
From DAC7 Address Verification to Payment Suspension: In What Order Does Inconsistency Usually Surface
This chain happens in this order because the cost of verification differs. Tax and identity information are compliance prerequisites, and the system can directly perform machine comparison against tax registration data and identity documents; if the comparison fails, a pending verification status is applied. At this point, the cost is the lowest, and usually you only need to submit one document.
The payment flow is much more serious. Once the payment account name, account opening entity, or withdrawal card holder does not match the registered entity, the platform and the payment institution enter risk control processes at the same time, and payments are stopped first rather than your being notified first. The first signal felt on the finance side is often not red text in the backend, but the settlement cycle arriving without the money.
The account layer is touched last and leaves the least room for explanation. When variables such as tax address, payment entity, and frequently used login region overlap across multiple accounts, the platform will not handle only the current account. This is consistent with Amazon's official explanation regarding multiple selling accounts: typically, one account per region, and multiple accounts may only be held when there is a legitimate business need, while a policy issue with one account may affect related accounts (seeAmazon Seller Forums explanation on multiple selling account health).
The six categories of account information Amazon cross-matches
First, break down “which materials need to be consistent.” The platform does not judge you based on a single field; instead, it sends the following six categories of information to different systems for verification, and any disconnect between any two categories can become a trigger point.
| Field category Specific content Referenced by Typical manifestation when inconsistent | |||
| Entity identity | Legal name, company registration number, legal representative ID documents | Identity verification, tax reporting, payment provider KYC | Name spelling or suffix differences cause verification failure |
| Registered address and tax address | Business license registered address, DAC7 tax residence, VAT registered address | Tax system, platform compliance review | Address verification requires supplementary supporting documents |
| Payee entity and withdrawal card | Receiving account name, account opening bank, and withdrawal cardholder | Payment institution KYC, platform fund flow | Payment suspension or fund hold |
| Contact information and billing address | Email, phone, and credit card billing address | Payment verification, notification delivery | Card verification failure, review notifications not received |
| Logistics shipping address | Shipping origin, return address, warehouse inbound information | Fulfillment authenticity verification, tax in the shipping country | Fulfillment or tax treatment is questioned |
| Login and operating environment | Network egress, browser Profile, device | Multi-account linkage determination | Other accounts in the same environment are also investigated |
The most easily overlooked categories in the table are the fifth and sixth. The logistics address appears to affect only shipping, but the shipping country determines in which country you incur tax obligations; the login environment appears unrelated to the information, yet it is the layer that binds the first five categories of information to 'a single operator.'
Address verification and DAC7 address validation: why the address is the most problematic field
Because the address is the only field referenced simultaneously by four systems. The business license registered address proves that the business entity actually exists; the tax residence determines tax attribution and is also the core information DAC7 requires to be reported; the billing address participates in payment verification; the logistics shipping address is linked to fulfillment authenticity and the shipping country. The four addresses point to different functions, yet share the same field name; if one is filled in incorrectly, the explanation cost for the other three increases.
Address verification and DAC7 address validation are not the same thing. Address verification is part of the platform-side document review, which usually requires submitting documents that prove 'this address belongs to this entity', such as a business license, lease contract, or utility bill. DAC7 address validation is tax information reporting; it determines where your tax residence is and which tax authority has jurisdiction over it. The two reference each other: if the tax residence you report in DAC7 falls in a different tax jurisdiction from the registered address in the backend, the review will require you to explain the discrepancy.
The key judgment is: inconsistency itself does not equal a violation.There can be differences between addresses, but the differences must be explainable by supporting documents.If the office address differs from the registered address, and you can provide the lease contract, business license, and tax registration at the same time, the review can usually pass; if you can only provide proof for one of the addresses, the other address becomes a dangling field, and the platform can only mark it as pending verification.
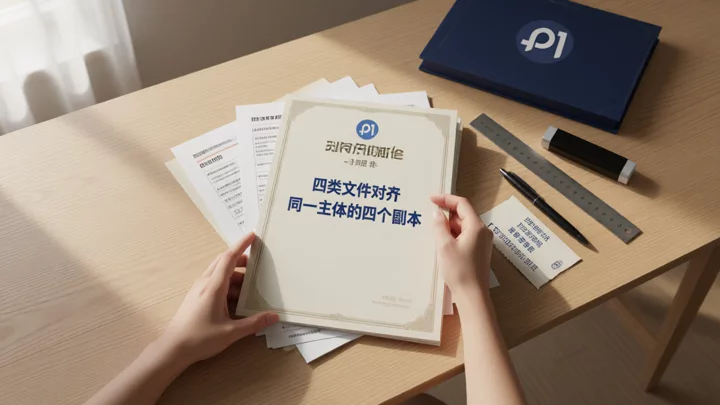 Only when the four types of information—identity, tax, funds, and logistics—point to the same entity does the review have a checkable basis.
In what order do the consequences of inconsistency appear?
- Information is pending verification or verification has failed.The correction window is at its widest; usually a single document supplement will resolve it. At this point, do not casually change other fields.
- Payment is paused or funds are placed on hold.The window begins to narrow. Tax information and the receiving entity must be handled at the same time, and the document supplementation cycle is measured in settlement cycles; one rejection means waiting an extra cycle.
- The account enters review.You are required to provide complete proof of the entity chain: registration documents, tax registration, ownership of the receiving account, and proof of business address—none can be missing. At this stage, explaining a single field is no longer enough.
- Other accounts in the same environment are investigated as well.This is the stage with the highest concentration of irreversible checkpoints. When funds are reserved and the account is under review at the same time, and you cannot produce proof of the entity chain, the initiative for recovery is basically no longer in your hands.
There is no "direct ban" step in the sequence. The vast majority of document issues first appear in the form of verification and funds; what is truly fatal is continuing to stack new inconsistencies within the verification window, such as casually changing the receiving account during document supplementation.
After discovering information inconsistencies, make changes in this order
- Freeze changes first.If you change tax information, receiving accounts, and the login environment at the same time while verification is in progress, the review will be unable to determine which set reflects your current true status. Stop first and document the current state clearly.
- Verify the entity identity.Compare the business license or company registration certificate word by word against the legal name in the backend, focusing on the suffix: whether Limited, Co., Ltd., or LLC is consistent, and whether the Chinese and English names correspond to the same registration number.
- Correct the tax information and DAC7 address.Use the tax registration documents as the basis, not where you actually work. If the tax residence differs from the registered address, submit documents that explain the relationship between the two together.
- Update the receiving account and withdrawal card.The name of the receiving entity must match the registered entity; if the withdrawal card holder is the legal representative personally, prepare documents proving their relationship to the entity. For the risk order of shared receiving accounts, see “What happens when several stores share one receiving account?” for a layer-by-layer breakdown.
- Finally, handle the environment.Each account has its own independent browser Profile, independent network egress, and independent activity trail. For environment-layer mechanisms, refer to “Amazon Multi-Store Operations from the Perspective of Browser Fingerprinting: Account Association Determination and Anti-Association Checklist.” Do not do this step ahead of time; there is no point in changing the environment before the information is aligned.
- After the changes, check three indicators.Whether the verification status in the backend changes from Pending Verification to Verified, whether the next payment plan is normal, and whether there are new policy alerts on the Account Health page. Only when all three are normal is this repair considered complete; if you move on to the next step just because the verification status has changed, the issue is likely to recur.
Multiple Accounts and Multiple Stores: Internally Consistent Within Each Account, Isolated Between Accounts
Two concepts need to be separated here. “Consistency” means that within the same account, the five sets of information—entity, tax, payment collection, logistics, and environment—point to the same entity; “association” means whether multiple accounts share variables. The former is mandatory, while the latter must be actively avoided.
Many people get these two things backwards: to make multiple accounts “look consistent,” they change the tax addresses, receiving accounts, and contact information of all stores to the same set, causing a surge in shared variables between accounts. The correct approach is for each account to keep its own information self-consistent, and for accounts not to share receiving accounts, tax addresses, contact information, or browser environments. Association determination looks at the combination of multiple variables rather than a single signal; the higher the overlap of variables across multiple layers, the greater the likelihood of being classified as controlled by the same person. For specific dimensions, see “When a platform determines whether several accounts belong to the same person, what dimensions does it usually look at?.”
The boundary for legitimate multiple accounts is still based on the official line: multiple accounts may be held when there is a legitimate business need, but each account must remain in good standing. This means you can have multiple accounts, but you cannot clone them using the same set of information, nor can you let one account’s problems spread to another account through shared variables.
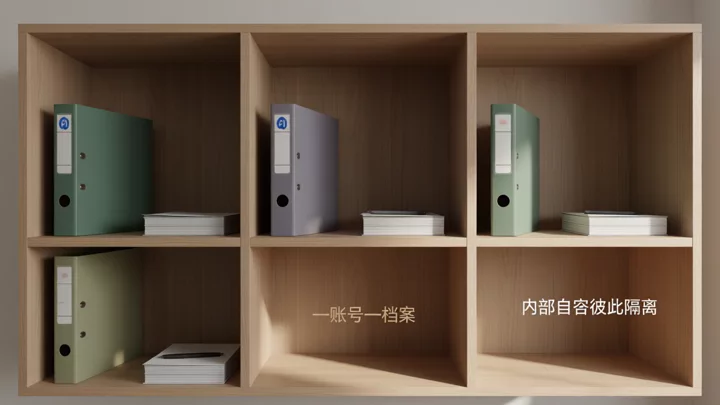 One account, one set of documents, and one environment: internally self-consistent and mutually isolated.
In day-to-day operations, that means one account corresponds to one set of entity documents, one tax address, one receiving account, and one independent browser Profile. When team personnel change or stores are handed over, the old browser environment and still-valid payment authorizations are the easiest entry points to miss; for the cleanup order, refer to “How to Ensure Account Security When Operations Staff Leave: Store Account Handover, Cross-Border E-Commerce Permission Handover, and Store Permission Checklist in Practice”. For specific multi-account environment configurations, including egress binding, Profile grouping, and daily switching habits, see “Amazon Multi-Account Management Practical Handbook (2026 Edition · Continuously Updated)” contains a checklist you can verify against.
Frequently Asked Questions
Amazon address verification says “inconsistent with registration information,” but I do live at that address. What should I do?
You need to distinguish between “you live here” and “this address can prove this entity.” What the review requires is the ownership relationship between the address and the entity, not the fact of residence. Submit documents that show both the entity name and the address (business license, lease contract, utility bills in the legal representative's name); documents that can only prove residence but not ownership are generally not accepted.
DAC7 requires you to fill in tax residence; why does it get blocked if it is inconsistent with the business license address?
The reason it gets blocked is not the inconsistency itself, but the lack of an explanation. Tax residence is determined by the place of actual management and tax obligation, and it is very common for it to fall in a different tax jurisdiction from the registered address, but you need to be able to present tax registration or proof of resident status to support this declaration. If you declare one address and the documents point to another, the system can only determine that the information cannot be verified.
If multiple stores use the same legal representative but different receiving accounts, are the documents considered consistent?
The premise for an account to be internally consistent is that each account's payment collection entity corresponds to its registered entity. The same legal person holding positions at different companies, with each company collecting payments separately, is self-consistent in each case; but if several accounts have the same registered entity and are merely split into different receiving accounts, the shared variables still exist, making this an association risk rather than a consistency solution.
After a business license address change, should the Amazon backend be updated first, or the bank and tax records?
Update the bank and tax records first, then update the backend. The backend contains facts that have already taken effect. If you update the backend first while other systems have not yet been updated, all cross-checks during that interim period will fall back to the old records, creating a window of inconsistency instead. After the change is complete, submit the full set of new documents at once.
If the receiving account name is missing a 'Limited Company' suffix compared with the registered entity, will it trigger a review?
It may trigger a review, or it may merely delay settlement. Payment institutions and platforms usually match names after normalization. Suffix differences can be tolerated in some banking systems, but if abbreviations, mixed Chinese and English, or punctuation differences are also present, the probability of being judged as different entities rises significantly. The safe approach is for the receiving account name to correspond exactly to the legal name on the registration certificate.